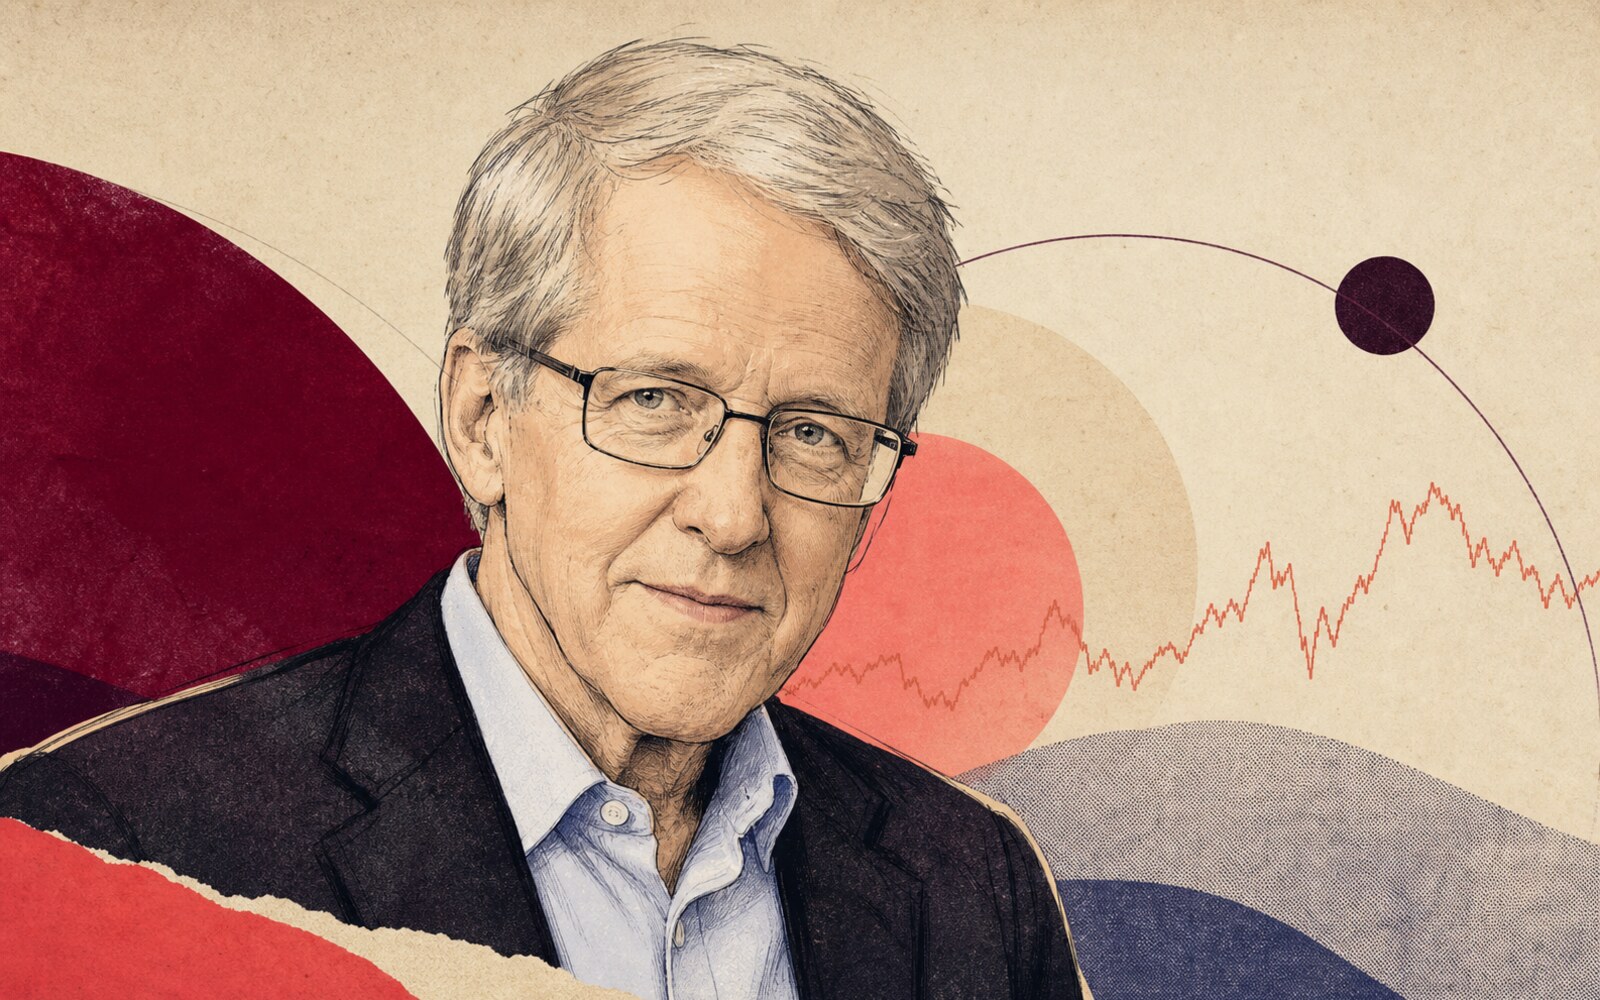
Quantitative finance is full of authors whose contributions have shaped how we understand markets, risk, and price behavior. From Harry Markowitz, who formalized modern portfolio theory, to Eugene Fama, who raised the efficient-market hypothesis to the status of dominant paradigm, by way of Fischer Black and Myron Scholes, whose option-pricing model permanently transformed financial practice, the discipline built over the twentieth century an analytical edifice of extraordinary sophistication. It was within this very edifice, however, that Robert James Shiller chose to work, not to inhabit it comfortably but to question some of its foundations. Today, March 29, Shiller turns 80, and the occasion justifies a pause to look carefully at the work of one of the most original and provocative economists of his generation.
Shiller was born in Detroit, Michigan, in 1946. He graduated from the University of Michigan in 1967 and went on to the Massachusetts Institute of Technology, where he earned his master’s degree in 1968 and his doctorate in 1972. At MIT he studied under central figures of modern macroeconomics and finance, and among his fellow doctoral students was Mario Draghi, who would later lead the European Central Bank. After appointments at the University of Minnesota and the University of Pennsylvania’s Wharton School, he settled at Yale in 1982, where he still teaches as Sterling Professor of Economics, the highest academic distinction the university confers.
Prices that move too much
A single thread runs through all of Shiller’s intellectual work: the conviction that financial markets are not rational in the sense mainstream theory assumes, and that ignoring this evidence has serious practical and theoretical consequences. For Shiller, this conviction was not the product of intuition or ideology, but of a precise and disturbing empirical result that he presented in 1981 in the pages of the American Economic Review, in an article whose title already read like an indictment: "Do Stock Prices Move Too Much to Be Justified by Subsequent Changes in Dividends?"
The argument starts from the fundamental asset-pricing equation. If markets are efficient and agents form rational expectations, the current price of a stock must equal the present value of its expected future dividends. A testable implication follows from this relationship: because the price observed today is the expectation of the rational ex post price (the price that would prevail if agents knew future dividends with certainty), the variance of the observed price must be less than or equal to the variance of that rational ex post price. Formally, the variance inequality implies \(\operatorname{Var}(P) \leq \operatorname{Var}(P^{\ast})\), where \(P^{\ast}\) is the ex post price calculated with perfect information about the future flow of dividends (SHILLER, 1981). Shiller tested this inequality using S&P Composite data going back to 1871, and the result was unequivocal: the variance of observed prices was systematically far greater than rational theory would allow. Prices moved excessively, far beyond what any rational revision of expectations about future dividends could justify. The key finding was that the present-value model implied a volatility incompatible with the data: stock prices were much more volatile than discounted future dividends would imply.
The article’s impact was immediate and lasting. What Shiller had identified became known as the excess volatility puzzle, and it generated an extensive literature of responses, criticisms, and extensions over the following decades. In parallel, working with John Y. Campbell, Shiller deepened the analysis of the relationships among prices, earnings, and expected returns. In their seminal 1988 article "Stock Prices, Earnings, and Expected Dividends", published in the Journal of Finance, Campbell and Shiller introduced the use of the CAPE ratio to forecast long-run stock-market returns. CAPE (the Cyclically Adjusted Price-to-Earnings ratio) is defined as the current price of a stock index divided by the average of inflation-adjusted real earnings over the previous ten years. The long-run average smooths out short-term earnings volatility and medium-term business cycles, making it a more faithful measure of companies’ long-run earning power. The logic of the smoothing is simple: annual earnings are too sensitive to the business cycle, and using them directly to value the market produces noisy signals that say little about the long-run path of returns. Using data going back to 1881, Campbell and Shiller showed that the lower the CAPE, the higher the expected return for investors over the following twenty years.
Bubbles, behavior, and narratives
The analytical tool only gained public prominence, however, when Shiller used it for diagnoses that most market participants preferred to ignore. In March 2000, at the very peak of the technology-stock bubble, he published Irrational Exuberance, in which he documented, with CAPE as a central instrument, that the U.S. stock market was trading at multiples wholly incompatible with any historical fundamental. In 2014, Shiller expressed concern about the level of CAPE, then above 25, a threshold that since 1881 had been exceeded in only three other periods: the years around 1929, 1999, and 2007, all followed by severe declines. The technology bubble burst a few months after the book came out. Years later, using the same methodology, he warned that U.S. housing prices were unsustainable, before the collapse that would trigger the 2008 financial crisis. The Case-Shiller Home Price Index, developed with Karl Case, became the standard benchmark for tracking the U.S. housing market and a central instrument in diagnosing the bubble of the 2000s.
The theory behind these forecasts is that asset markets form speculative bubbles: periods in which prices systematically detach from any fundamental anchor and come to be sustained by the self-fulfilling expectation of continued appreciation. For Shiller, this is not a passing anomaly but a recurring feature of markets inhabited by human beings whose decisions are shaped by collective narratives, by emotions, and by herd behavior. This conviction made him one of the founders of behavioral economics applied to finance, a field that seeks to bring insights from psychology into the study of markets. In Animal Spirits (2009), coauthored with George Akerlof, winner of the 2001 Nobel Prize, Shiller argued that psychological variables such as confidence, perceived fairness, and susceptibility to narratives have a causal influence on macroeconomic variables such as consumption, investment, and employment, phenomena that rational-expectations models treat as noise or anomaly. This line of research culminated in Narrative Economics (2019), in which Shiller proposes that stories spreading virally through society have causal power over aggregate economic behavior, just as a virus spreads through a population, affecting decisions about consumption, investment, and saving in a coordinated and sometimes destabilizing way.
In 2013, Shiller received the Nobel Memorial Prize in Economic Sciences, shared with Eugene Fama and Lars Peter Hansen, for the empirical analysis of asset prices. The irony of the award did not go unnoticed: Fama and Shiller represent almost opposite views of how markets work, and they shared the stage in Stockholm without the tension between their bodies of work having been fully resolved. Fama showed that short-run prices are essentially unpredictable; Shiller showed that long-run prices display mean-reversion patterns that make them at least partly predictable. Both are right, at different time horizons, and it is precisely this unresolved tension that makes the field so fertile. At 80, Robert Shiller remains active, and the best tribute one can pay on his birthday is to read what he wrote with a willingness to be made uncomfortable.
References
AKERLOF, George A.; SHILLER, Robert J. Animal Spirits: How Human Psychology Drives the Economy and Why It Matters for Global Capitalism. Princeton: Princeton University Press, 2009.
CAMPBELL, John Y.; SHILLER, Robert J. Stock prices, earnings, and expected dividends. The Journal of Finance, v. 43, n. 3, p. 661-676, July 1988.
SHILLER, Robert J. Do stock prices move too much to be justified by subsequent changes in dividends? The American Economic Review, v. 71, n. 3, p. 421-436, June 1981.
SHILLER, Robert J. Irrational Exuberance. Princeton: Princeton University Press, 2000.
SHILLER, Robert J. Speculative asset prices. The American Economic Review, v. 104, n. 6, p. 1486-1517, June 2014. (Nobel Prize Lecture)
SHILLER, Robert J. Narrative Economics: How Stories Go Viral and Drive Major Economic Events. Princeton: Princeton University Press, 2019.